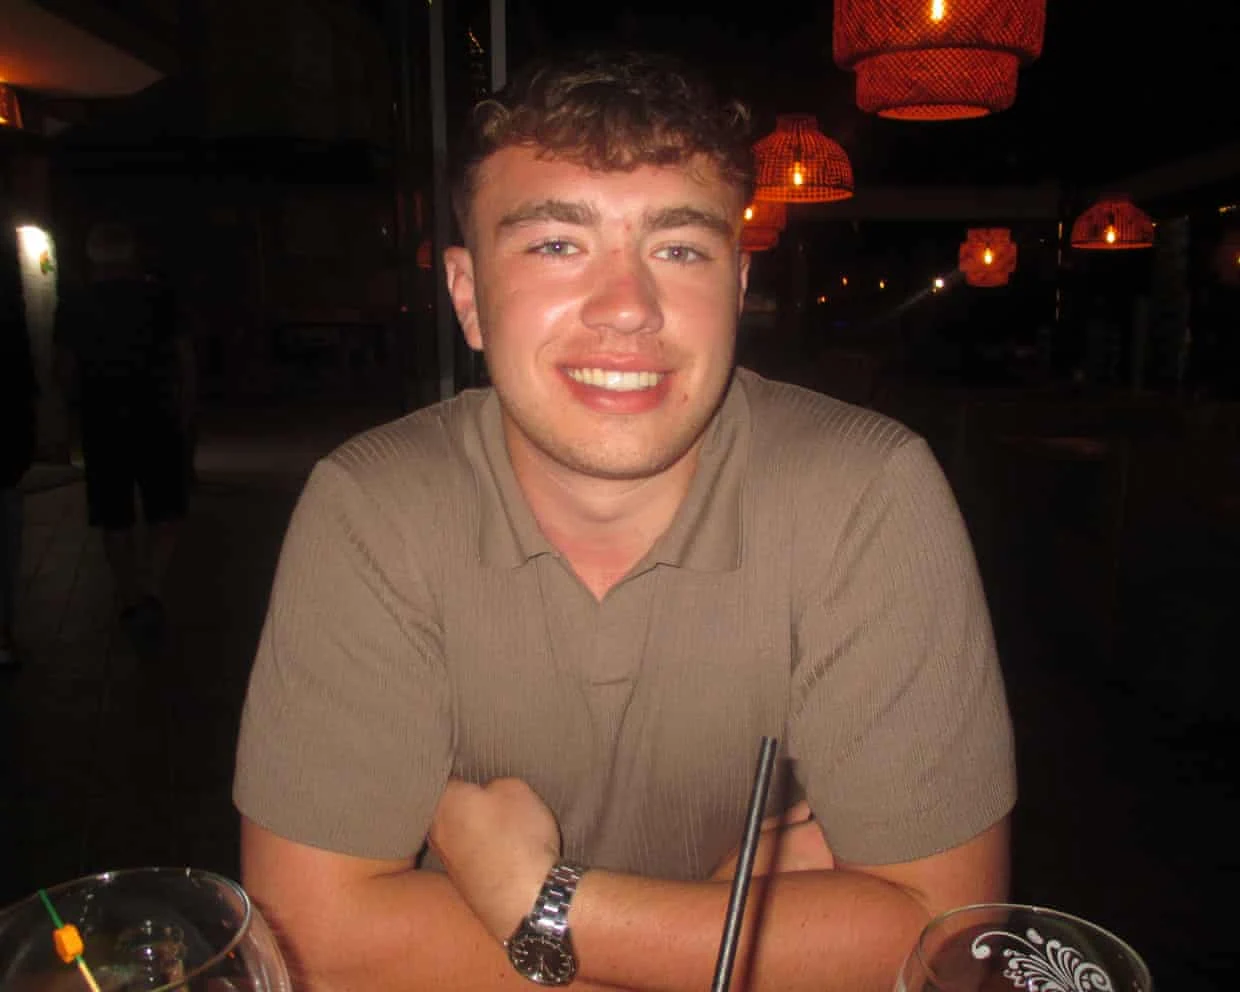
Rio is pleased he had the chat, and now has a pot of £8,000 and counting. Photograph: Supplied
A young worker named Rio initially declined his employer's pension scheme because he wanted to keep more of his pay. He had started work at 18, before becoming old enough for automatic enrolment under the existing system. The Guardian
Key facts
The UK system introduced in 2012 generally requires enrolment from age 22 for employees earning more than £10,000 annually. The Guardian
The standard minimum contribution described in the report totals 8%, including the worker's contribution, tax relief and at least 3% from the employer. The Guardian
Money invested early has longer to earn returns, and those returns can themselves generate further growth. The Guardian
A conversation changes an early pension decision
Rio was 18 when he started work as a technical trainee and decided a workplace pension cost too much. Nearly two years later, after advice from his aunt, his own contributions total about £2,000 and his fund is worth approximately £8,000. The Guardian uses his experience to explain why waiting for automatic enrolment can mean missing employer contributions. The increase in his fund reflects more than investment performance: his employer and tax relief added substantial amounts alongside his payments.
Automatic enrolment does not begin for every worker at 18
The UK system introduced in 2012 generally requires enrolment from age 22 for employees earning more than £10,000 annually. Younger workers can ask to join from 16 instead of waiting to meet the automatic criteria. Rio was offered that choice when he began his job in September 2024. The important distinction is between not yet being enrolled automatically and being unable to participate at all. Whether joining triggers employer payments also depends on the relevant eligibility rules and scheme arrangements. Reporting context: The Guardian
Rio's employer offered more than the minimum
The standard minimum contribution described in the report totals 8%, including the worker's contribution, tax relief and at least 3% from the employer. Rio's scheme was more generous: paying 5% of his earnings unlocked a 10% employer contribution. His aunt, Scottish Widows pensions specialist Susan Hope, calculated that his personal cost of £83 a month produced £312 going into the pension after employer contributions and tax relief. That is an example from his particular scheme, not a standard return available to everyone. Reporting context: The Guardian
Compounding rewards time, without guaranteeing a result
Money invested early has longer to earn returns, and those returns can themselves generate further growth. Hope estimated that four years of contributions before age 22 could leave Rio with an additional £110,000 after 40 years, assuming 5% investment growth. The assumption is essential to the projection. Future performance is uncertain, and the estimate is not a promised balance. The illustration shows how a relatively short period at the beginning of working life can have a much larger effect over several decades. Reporting context: The Guardian
The immediate trade-off remains real
Rio initially focused on having less money to spend now. The pension contributions still reduced his current disposable income after he joined; advice changed his understanding of what he received in exchange. Employer contributions and tax relief made the decision look different from simply moving his own money into another account. For young workers, understanding the scheme therefore involves both present affordability and the value of payments available only when they participate. The story does not suggest every household has the same room in its budget.
Basic questions can uncover valuable information
A PensionBee survey cited in the report found 49% of savers had avoided a pension question because they feared it was too basic. Only 13% described themselves as very confident about how their pension works. The practical lesson from Rio's experience is to establish contribution levels, employer matching and scheme terms rather than assume that waiting costs nothing. His aunt happened to be an expert, but the underlying questions are ordinary ones about how money reaches a retirement fund and what is forgone by staying outside it. Reporting context: The Guardian
Sources and editorial notes
This article compiles the linked reporting. Allegations, projections and research findings retain their original qualifications; this page does not represent independent field reporting or expert medical review.
- The Guardian (reporting)
November 17, 2026: Replaced repeated summary and FAQ templates, added source attribution and image description, and clarified the distinction between source publication and site edits. This editorial update is not an independent fact-check certification.